Track 02Module 2 of 611 sources
Volatility: implied, realised, skew and term structure
Decide whether options are cheap or expensive by comparing implied volatility with realised, and read skew and term structure as positioning.
Key ideas
- Implied volatility is usually above what is later realised. That gap, the variance risk premium, is the insurance premium sellers earn for carrying crash risk.
- The at-the-money straddle price is the market's own estimate of the move to expiry. A quick rule: daily move is roughly annual volatility divided by 16.
- Skew exists because investors pay up for downside protection. Steepening skew means rising demand for puts.
- A normal term structure slopes up. When near-term volatility trades above longer-term, the market is pricing stress now.
Start hereWatch or read these first. They carry the core idea.
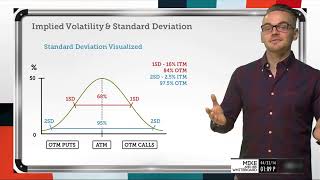
Implied Volatility & Standard Deviation Explained
Video · tastylive · 16:48
Implied volatility as an expected range, with the standard deviation arithmetic.
Report
Understanding the Volatility Risk Premium
AQR · 2018
A clear paper on why implied exceeds realised, how large the premium is and when it fails.
CoreThe standard references. Work through them once the idea is clear.
Implied Volatility, Volatility Skew, and the Term Structure of Volatility
Video · Mark Meldrum · 35:08
Skew and term structure taught at exam standard.
Book
Volatility Trading
Euan Sinclair
How to measure, forecast and trade volatility. The chapter on the variance premium is essential.
Master Volatility Options Trading with Dr. Euan Sinclair | Advanced Strategies Explained
Video · QuantInsti Quantitative Learning · 1:02:21
The same author on how professionals actually find an edge in volatility.
PDF
Cboe Volatility Index (VIX) Methodology
Cboe
How the VIX is computed from option prices. India VIX uses the same method.
Paper
Variance Risk Premiums
Carr, Wu · 2008 · Review of Financial Studies · doi:10.1093/rfs/hhn038
The academic measurement of the variance risk premium across indices and stocks.
Site
Cboe Insights: volatility and flow commentary
Cboe
Regular commentary on volatility and flow from the exchange.
Newsletter
Party at the Moontower (Kris Abdelmessih on options thinking)
Moontower
A former options market maker writing about how to think in volatility.
Go deeperResearch, primary sources and data for when you want the detail.
Paper
Does Net Buying Pressure Affect the Shape of Implied Volatility Functions?
Bollen, Whaley · 2004 · The Journal of Finance · doi:10.1111/j.1540-6261.2004.00647.x
Evidence that buying pressure, not just expectations, shapes the skew.
Book
Practice
For two weeks, log India VIX, Nifty's 20-day realised volatility and the at-the-money straddle price. Note on which days implied was above realised and by how much.
See it live
Connections: the VIX term structure and volatility inferences →Desk: implied move for Nifty and SPY →
Where this leads
02.3 · Options and Options FlowDealer positioning: gamma, vanna, charm and pinningExplain how dealer hedging can dampen or amplify moves, and read a gamma exposure estimate with the right amount of doubt.08.3 · Risk, Losses and ProcessLeverage, crowding and blow-upsRecognise the conditions that turn a good trade into a disaster: leverage, crowding and liquidity that vanishes.